2. Is the budget higher? FY27 vs FY26 vs FY26 actual
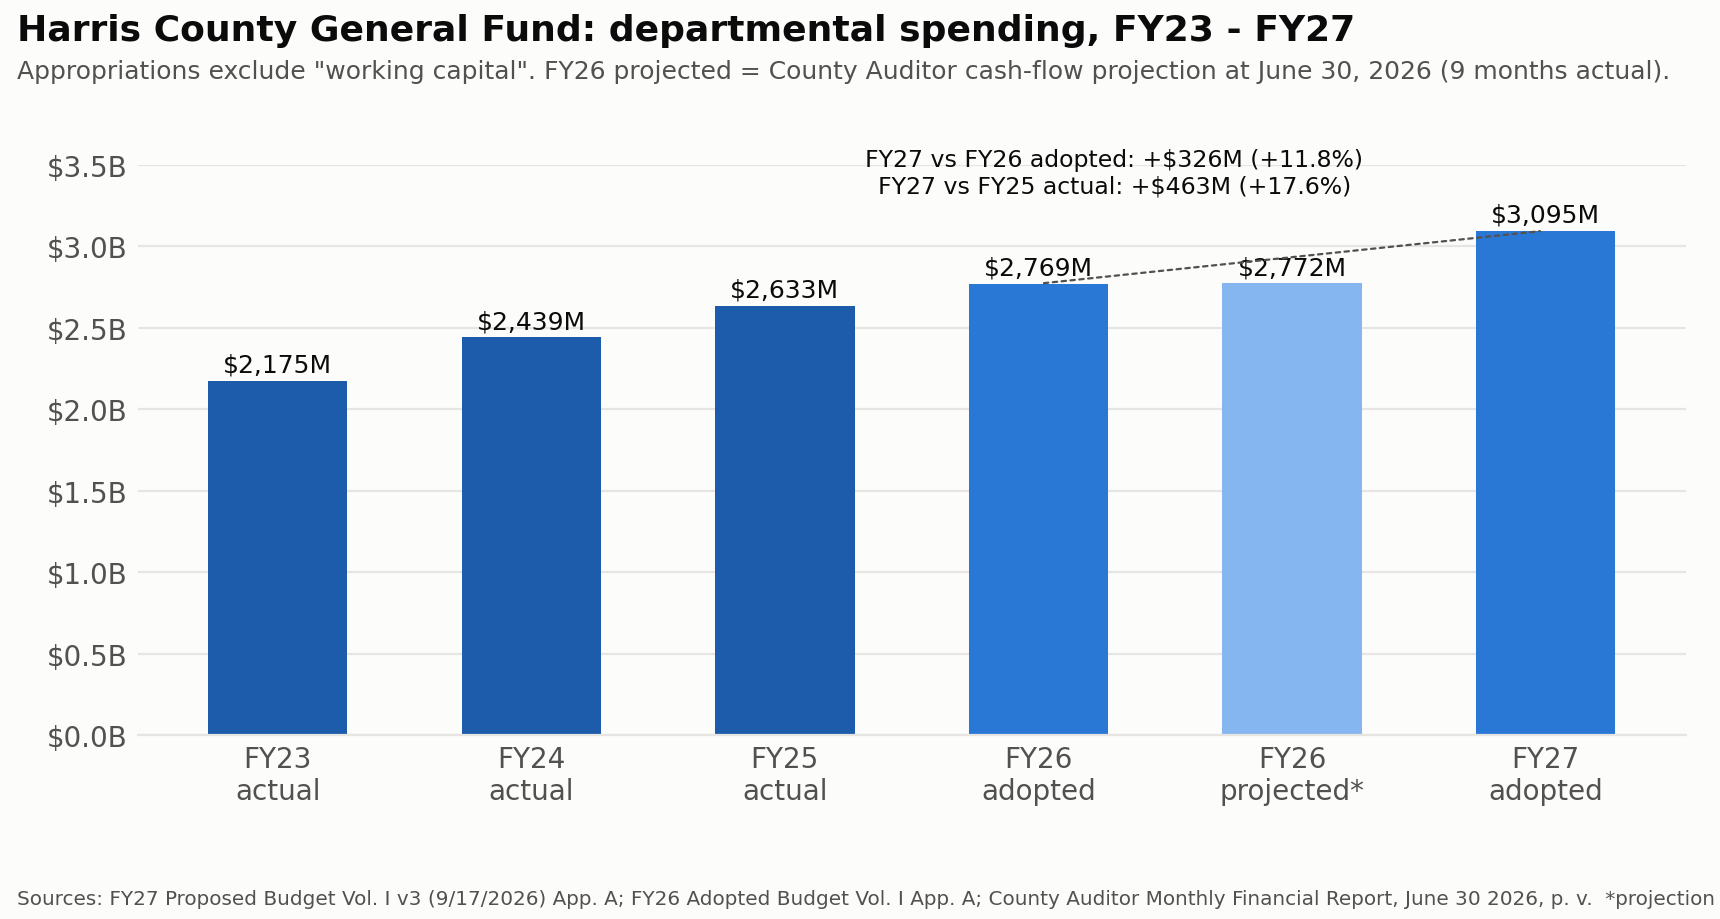
Figure 1. General Fund departmental appropriations and actuals. FY26 projected is the County Auditor's cash-flow projection as of June 30, 2026.
| Measure | FY25 | FY26 | FY27 | FY27 vs FY26 |
|---|---|---|---|---|
| Departmental appropriations (Appendix A) | $2,669.4M | $2,769.4M | $3,095.4M | +$326.0M (+11.8%) |
| Actual / projected spending (cash basis, incl. transfers out) | $2,632.5M | $2,772.2M (proj.) | n/a | FY27 budget vs FY26 proj.: +11.7% |
| Working capital (unallocated + Court rollover) | $237.6M | $345.1M | $256.0M | $-89.1M |
| Total appropriation authority (Auditor's estimate of available resources) | $2,907.1M | $3,114.5M | $3,351.4M | +$236.9M (+7.6%) |
| General Fund revenue (OMB projection) | $2,702.0M | $2,765.0M | $3,079.4M | +$314.4M (+11.4%) |
| Salaries and benefits (cash basis) | $1,756.7M | $1,987.7M (proj.) | n/a | FY26 9-month actuals +13.45% YoY |
Table 1. Sources: FY27 Vol. I v3 Appendix A (p. 105) and p. 27, 40; FY26 Vol. I p. 97; Auditor monthly reports Sept. 30, 2025 and June 30, 2026; Auditor FEAR FY2026.
Reading the numbers. Harris County budgets on a cash basis and, by statute, cannot appropriate more than the County Auditor's "Final Estimate of Available Resources" (FEAR), which is beginning cash plus expected revenue. The county has for years appropriated departmental budgets well below the FEAR and labels the difference "working capital". Press releases and news reports quote the departmental figure ($3,095M, +11.8%); the county's statutory Tax Code Sec. 26.18 posting reports the FEAR-based total ($3,351M, +7.6%). Both are correct. The working-capital line fell from $345M to $256M, but that is a budget residual (certified resources of $3,351.4M, i.e. $387.0M of beginning cash plus $2,964.3M of certified revenue, less the $3,095.4M appropriated), not a measure of cash the county plans to consume. The telling comparison is a different one: OMB's $3,079.4M revenue forecast exceeds the Auditor's certified revenue by $115.1M, which the book explains as receipts the Auditor will certify only when they are sufficiently certain or received. Against certified revenue alone, departmental appropriations exceed revenue by $131.1M, covered by beginning cash if the anticipated receipts do not arrive. The county publishes no source-by-source list of the $115.1M.
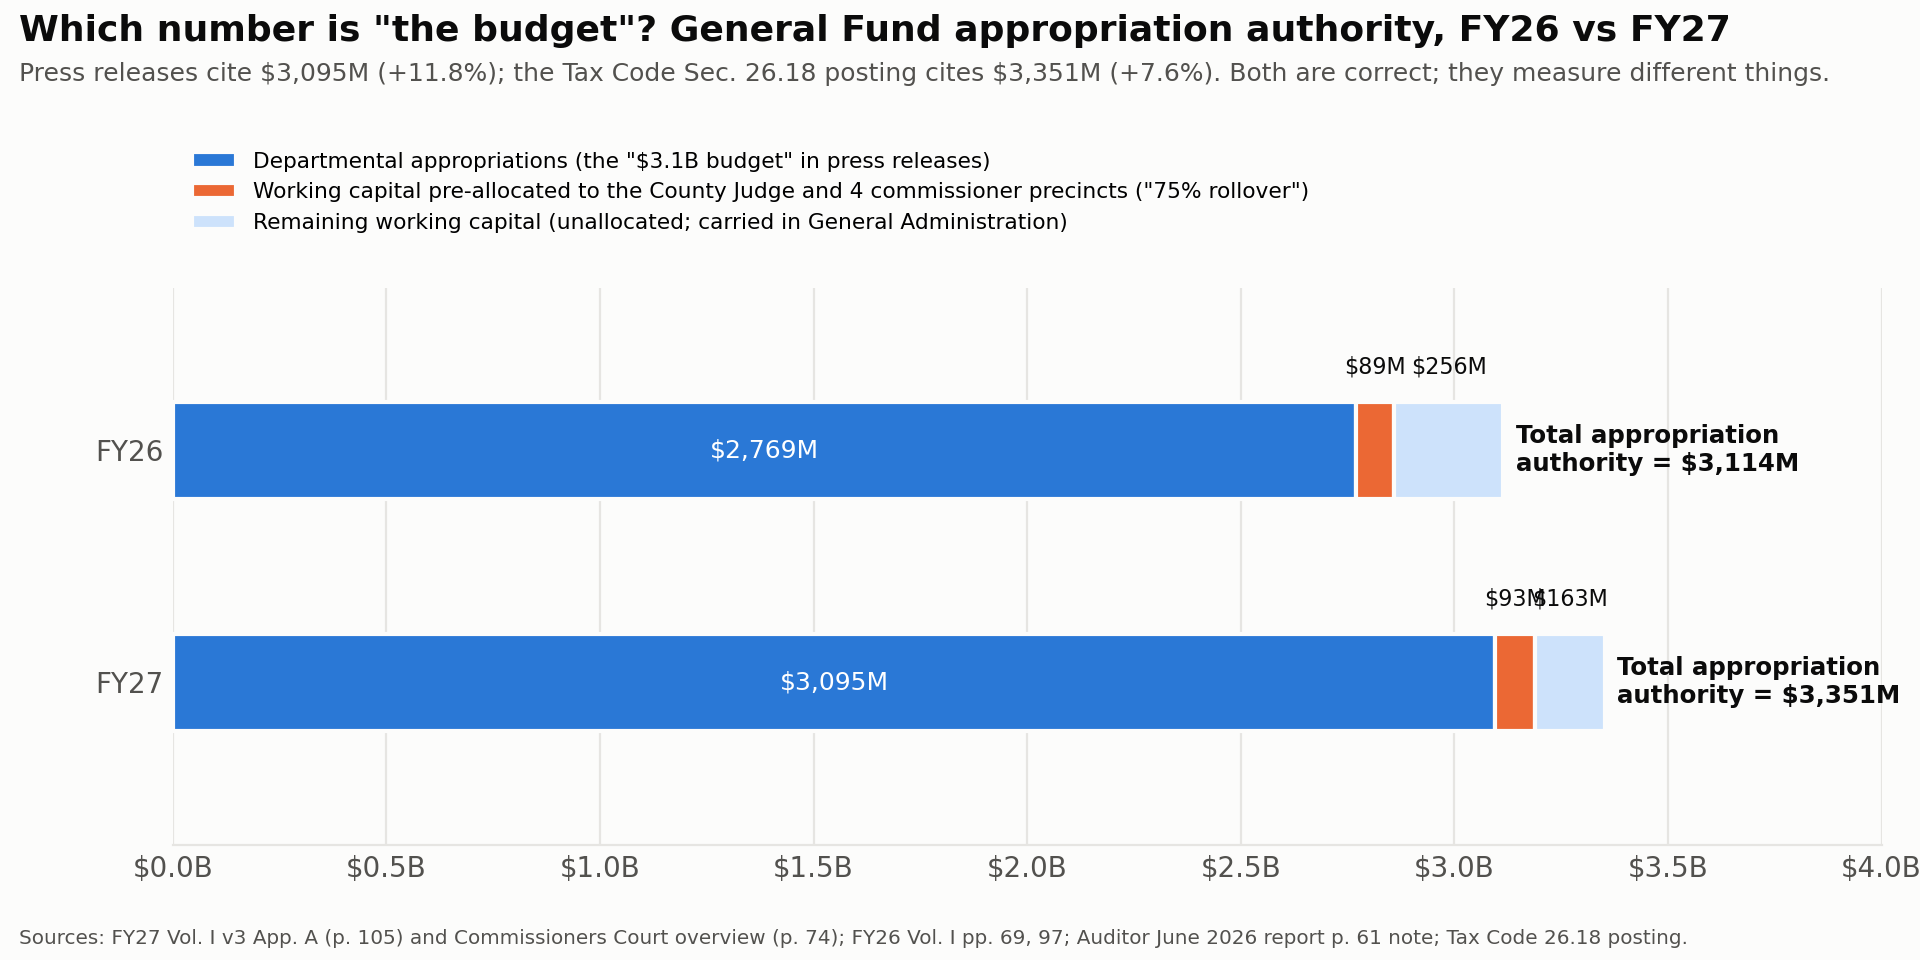
Figure 2. The three layers of General Fund appropriation authority. The orange segment is the "75% of estimated ending balance" carried forward for the County Judge and commissioners (FY26: $88.9M; FY27: $93.4M); it is added to their departmental budgets in a separate table (Vol. I v3 p. 74) and is not part of the $3,095M.
FY26 in practice. The Auditor's June 30, 2026 report shows the General Fund had spent $2,048.3M in nine months (65.6% of the $3,120.8M adjusted budget, or 87% counting $667.0M of encumbrances), with salaries and benefits up 13.45%, services down 8.1% and capital outlay down 82.9% year over year. Its cash-flow projection puts full-year FY26 spending at $2,772.2M and revenue at $2,754.7M. Spending and transfers therefore exceed receipts by $17.5M; ending cash is still projected at $391.9M, above the $383.6M the year began with, because of $26.9M of other sources. That is a cash forecast, not an audited result, and it holds only after the $25M hiring freeze, $78M of jail medical costs shifted to Harris Health, and one-time transfers that FY27 has to replace.